Medical
Forvis Mazars offers two medical plan options designed to support a variety of healthcare needs and budgets. These plans are administered by UnitedHealthcare and provide access to a nationwide network of quality providers and facilities. Choosing in-network providers helps maximize your benefits and minimize your out-of-pocket expenses. If you receive care from an out-of-network provider, you may be responsible for additional costs beyond the plan’s covered amount.
Choosing the right medical plan is like choosing the right car. When buying a car, you take into consideration the cost of the car along with related expenses such as insurance and gas.
Apply the same logic to making the right medical plan decision. First consider the premium. Then think about expenses the plans does not cover such as deductibles and coinsurance.
|
HDHP & HDHP CA |
Choice Plus & Select Plus CA |
|
|---|---|---|
| Overview | Lower monthly premiums with a higher deductible. Includes an HSA to help you save for eligible health care expenses. | Higher monthly premiums with lower deductible and copays for predictable out-of-pocket costs. |
| In-network deductible | $1,800 | $800 |
| Out-of-pocket max | $5,000 | $4,000 |
| Preventive services | 100% Covered | 100% Covered |
| Primary care visit | 20% After Deductible | $20 |
| Specialist visit | 20% After Deductible | $40 |
| Urgent care | 20% After Deductible | $40 |
| Emergency room | 20% After Deductible | $300 + 20% After Deductible |
| Your Monthly Premium | $153 | $295 |
HDHP + HSA:
The High Deductible Health Plan can be paired with a Health Savings Account (HSA), giving you a tax-advantaged way to save and pay for eligible health care expenses.Choice Plus + FSA:
The Choice Plus plan can be paired with a Flexible Spending Account (FSA), allowing you to contribute pre-tax dollars and use those funds for eligible medical expenses.
Choosing between the two plans is a very important and personal decision. As you make your selection, there are many things to consider. See some examples below:
Assess your typical annual health care costs
- Do you anticipate your costs to increase, decrease, or stay the same for the coming year?
- Did you meet your deductible last year?
- How would you have fared if you were on the other plan the previous year—would you have been in a better or worse position?
Consider the tax savings options for each plan
- Both medical plans offer tax-saving opportunities, but the account available depends on the plan you choose.
- Choice Plus plans can be paired with a Flexible Spending Account (FSA). An FSA allows you to set aside pre-tax dollars that can be used toward eligible health care expenses throughout the year. Once enrolled, your annual contribution election generally cannot be changed unless you experience a qualifying life event. If you do not use all of your FSA funds during the plan year, you may carry over up to $680 into the following year. Any amount above the carryover limit will be forfeited.
- The High Deductible Health Plan (HDHP) can be paired with a Health Savings Account (HSA). An HSA allows you to contribute tax-free dollars that can be used toward eligible health care expenses. Unlike an FSA, unused HSA funds roll over from year to year, allowing you to save for future health care needs. HSA funds may also earn interest or be invested, depending on your account balance and investment elections.
- Please see the Tax Savings Accounts section for additional information about these accounts and their features.
Weigh the reward against the risk
- Both plans will provide you and your family with comprehensive medical coverage. Deciding which plan to select may come down to choosing between the reward of spending less in premiums and potential risk of paying more in deductibles and out-of-pocket maximums if you experience a health issue.
To assist with estimating potential out-of-pocket expenses for both plans, an Employee Medical Plan Cost Calculator is available in the Key Resources section of this page. Do the math and determine which plan is the best fit for you and your family’s personal and financial situation.
After your initial medical insurance election with UHC, you should receive a physical ID card via postal mail within 5 – 7 business days of your insurance coverage becoming active. For all subsequent updates to your coverage, new ID cards will only be delivered electronically. You can still request a physical ID card at any time via the myUHC portal or by contacting United Healthcare at 1-844-638-8700.
As health care costs continue to rise, we should look for ways to control costs where we can. With a self-funded plan, both Forvis Mazars and the participants should be wise health care consumers. Please keep in mind the tips below as you weigh your health care options.
Use In-Network Providers
Using in-network providers generates higher discounts, reducing overall plan costs and out-of-pocket expenses.
Seek the Appropriate Level of Care
Seeking the appropriate level of care helps reduce overall plan costs and maintain the continuity of care. An emergency room visit can cost more than seven times what physician’s office or urgent care visits typically cost.
- Take advantage of the 100 percent coverage for preventive care, which may result in early detection and increase prevention awareness.
- Be informed about the cost of tests and treatment plans.
Effective January 1, 2023, eligible employees and partners retiring from the firm can continue to remain on the Forvis Mazars Medical, Dental and Vision plans until they meet the eligibility requirements for Medicare. When the retiree becomes Medicare eligible, their spouse can remain on the plan(s) until they become Medicare eligible. Dependent children can remain on the plan until they reach age 26 or otherwise maintain eligibility.
To be considered a retiree, you must be at least age 52, with the sum of the retiree’s age and years of service (including with a legacy firm) equaling 65 or more and be enrolled in the applicable plan(s) at the time of retirement.
Forvis Mazars does not contribute any funds towards the cost of the retiree coverage. The premiums for retiree coverage are fully paid for by the retiree (or dependents, if applicable). The Medical premiums are 145 percent of the monthly premium for 2027, and the Dental and Vision premiums are 100 percent of the full monthly premium.
|
HDHP & HDHP CA |
Choice Plus & Select Plus CA |
|
|---|---|---|
| Overview | Lower monthly premiums with a higher deductible. Includes an HSA to help you save for eligible health care expenses. | Higher monthly premiums with lower deductible and copays for predictable out-of-pocket costs. |
| In-network deductible | $3,600 |
$800 individual (embedded) $1,600 family |
| Out-of-pocket max | $10,000 family |
$4,000 individual (embedded) $8,000 family |
| Preventive services | 100% Covered | 100% Covered |
| Primary care visit | 20% After Deductible | $20 |
| Specialist visit | 20% After Deductible | $40 |
| Urgent care | 20% After Deductible | $40 |
| Emergency room | 20% After Deductible | $300 + 20% After Deductible |
| Your Monthly Premium | $335 | $646 |
HDHP + HSA:
The High Deductible Health Plan can be paired with a Health Savings Account (HSA), giving you a tax-advantaged way to save and pay for eligible health care expenses.Choice Plus + FSA:
The Choice Plus plan can be paired with a Flexible Spending Account (FSA), allowing you to contribute pre-tax dollars and use those funds for eligible medical expenses.
Choosing between the two plans is a very important and personal decision. As you make your selection, there are many things to consider. See some examples below:
Assess your typical annual health care costs
- Do you anticipate your costs to increase, decrease, or stay the same for the coming year?
- Did you meet your deductible last year?
- How would you have fared if you were on the other plan the previous year—would you have been in a better or worse position?
Consider the tax savings options for each plan
- Both medical plans offer tax-saving opportunities, but the account available depends on the plan you choose.
- Choice Plus plans can be paired with a Flexible Spending Account (FSA). An FSA allows you to set aside pre-tax dollars that can be used toward eligible health care expenses throughout the year. Once enrolled, your annual contribution election generally cannot be changed unless you experience a qualifying life event. If you do not use all of your FSA funds during the plan year, you may carry over up to $680 into the following year. Any amount above the carryover limit will be forfeited.
- The High Deductible Health Plan (HDHP) can be paired with a Health Savings Account (HSA). An HSA allows you to contribute tax-free dollars that can be used toward eligible health care expenses. Unlike an FSA, unused HSA funds roll over from year to year, allowing you to save for future health care needs. HSA funds may also earn interest or be invested, depending on your account balance and investment elections.
- Please see the Tax Savings Accounts section for additional information about these accounts and their features.
Weigh the reward against the risk
- Both plans will provide you and your family with comprehensive medical coverage. Deciding which plan to select may come down to choosing between the reward of spending less in premiums and potential risk of paying more in deductibles and out-of-pocket maximums if you experience a health issue.
To assist with estimating potential out-of-pocket expenses for both plans, an Employee Medical Plan Cost Calculator is available in the Key Resources section of this page. Do the math and determine which plan is the best fit for you and your family’s personal and financial situation.
After your initial medical insurance election with UHC, you should receive a physical ID card via postal mail within 5 – 7 business days of your insurance coverage becoming active. For all subsequent updates to your coverage, new ID cards will only be delivered electronically. You can still request a physical ID card at any time via the myUHC portal or by contacting United Healthcare at 1-844-638-8700.
As health care costs continue to rise, we should look for ways to control costs where we can. With a self-funded plan, both Forvis Mazars and the participants should be wise health care consumers. Please keep in mind the tips below as you weigh your health care options.
Use In-Network Providers
Using in-network providers generates higher discounts, reducing overall plan costs and out-of-pocket expenses.
Seek the Appropriate Level of Care
Seeking the appropriate level of care helps reduce overall plan costs and maintain the continuity of care. An emergency room visit can cost more than seven times what physician’s office or urgent care visits typically cost.
- Take advantage of the 100 percent coverage for preventive care, which may result in early detection and increase prevention awareness.
- Be informed about the cost of tests and treatment plans.
Effective January 1, 2023, eligible employees and partners retiring from the firm can continue to remain on the Forvis Mazars Medical, Dental and Vision plans until they meet the eligibility requirements for Medicare. When the retiree becomes Medicare eligible, their spouse can remain on the plan(s) until they become Medicare eligible. Dependent children can remain on the plan until they reach age 26 or otherwise maintain eligibility.
To be considered a retiree, you must be at least age 52, with the sum of the retiree’s age and years of service (including with a legacy firm) equaling 65 or more and be enrolled in the applicable plan(s) at the time of retirement.
Forvis Mazars does not contribute any funds towards the cost of the retiree coverage. The premiums for retiree coverage are fully paid for by the retiree (or dependents, if applicable). The Medical premiums are 145 percent of the monthly premium for 2027, and the Dental and Vision premiums are 100 percent of the full monthly premium.
|
HDHP & HDHP CA |
Choice Plus & Select Plus CA |
|
|---|---|---|
| Overview | Lower monthly premiums with a higher deductible. Includes an HSA to help you save for eligible health care expenses. | Higher monthly premiums with lower deductible and copays for predictable out-of-pocket costs. |
| In-network deductible | $3,600 |
$800 individual (embedded) $1,600 family |
| Out-of-pocket max | $10,000 family |
$4,000 individual (embedded) $8,000 family |
| Preventive services | 100% Covered | 100% Covered |
| Primary care visit | 20% After Deductible | $20 |
| Specialist visit | 20% After Deductible | $40 |
| Urgent care | 20% After Deductible | $40 |
| Emergency room | 20% After Deductible | $300 + 20% After Deductible |
| Your Monthly Premium | $287 | $572 |
HDHP + HSA:
The High Deductible Health Plan can be paired with a Health Savings Account (HSA), giving you a tax-advantaged way to save and pay for eligible health care expenses.Choice Plus + FSA:
The Choice Plus plan can be paired with a Flexible Spending Account (FSA), allowing you to contribute pre-tax dollars and use those funds for eligible medical expenses.
Choosing between the two plans is a very important and personal decision. As you make your selection, there are many things to consider. See some examples below:
Assess your typical annual health care costs
- Do you anticipate your costs to increase, decrease, or stay the same for the coming year?
- Did you meet your deductible last year?
- How would you have fared if you were on the other plan the previous year—would you have been in a better or worse position?
Consider the tax savings options for each plan
- Both medical plans offer tax-saving opportunities, but the account available depends on the plan you choose.
- Choice Plus plans can be paired with a Flexible Spending Account (FSA). An FSA allows you to set aside pre-tax dollars that can be used toward eligible health care expenses throughout the year. Once enrolled, your annual contribution election generally cannot be changed unless you experience a qualifying life event. If you do not use all of your FSA funds during the plan year, you may carry over up to $680 into the following year. Any amount above the carryover limit will be forfeited.
- The High Deductible Health Plan (HDHP) can be paired with a Health Savings Account (HSA). An HSA allows you to contribute tax-free dollars that can be used toward eligible health care expenses. Unlike an FSA, unused HSA funds roll over from year to year, allowing you to save for future health care needs. HSA funds may also earn interest or be invested, depending on your account balance and investment elections.
- Please see the Tax Savings Accounts section for additional information about these accounts and their features.
Weigh the reward against the risk
- Both plans will provide you and your family with comprehensive medical coverage. Deciding which plan to select may come down to choosing between the reward of spending less in premiums and potential risk of paying more in deductibles and out-of-pocket maximums if you experience a health issue.
To assist with estimating potential out-of-pocket expenses for both plans, an Employee Medical Plan Cost Calculator is available in the Key Resources section of this page. Do the math and determine which plan is the best fit for you and your family’s personal and financial situation.
After your initial medical insurance election with UHC, you should receive a physical ID card via postal mail within 5 – 7 business days of your insurance coverage becoming active. For all subsequent updates to your coverage, new ID cards will only be delivered electronically. You can still request a physical ID card at any time via the myUHC portal or by contacting United Healthcare at 1-844-638-8700.
As health care costs continue to rise, we should look for ways to control costs where we can. With a self-funded plan, both Forvis Mazars and the participants should be wise health care consumers. Please keep in mind the tips below as you weigh your health care options.
Use In-Network Providers
Using in-network providers generates higher discounts, reducing overall plan costs and out-of-pocket expenses.
Seek the Appropriate Level of Care
Seeking the appropriate level of care helps reduce overall plan costs and maintain the continuity of care. An emergency room visit can cost more than seven times what physician’s office or urgent care visits typically cost.
- Take advantage of the 100 percent coverage for preventive care, which may result in early detection and increase prevention awareness.
- Be informed about the cost of tests and treatment plans.
Effective January 1, 2023, eligible employees and partners retiring from the firm can continue to remain on the Forvis Mazars Medical, Dental and Vision plans until they meet the eligibility requirements for Medicare. When the retiree becomes Medicare eligible, their spouse can remain on the plan(s) until they become Medicare eligible. Dependent children can remain on the plan until they reach age 26 or otherwise maintain eligibility.
To be considered a retiree, you must be at least age 52, with the sum of the retiree’s age and years of service (including with a legacy firm) equaling 65 or more and be enrolled in the applicable plan(s) at the time of retirement.
Forvis Mazars does not contribute any funds towards the cost of the retiree coverage. The premiums for retiree coverage are fully paid for by the retiree (or dependents, if applicable). The Medical premiums are 145 percent of the monthly premium for 2027, and the Dental and Vision premiums are 100 percent of the full monthly premium.
|
HDHP & HDHP CA |
Choice Plus & Select Plus CA |
|
|---|---|---|
| Overview | Lower monthly premiums with a higher deductible. Includes an HSA to help you save for eligible health care expenses. | Higher monthly premiums with lower deductible and copays for predictable out-of-pocket costs. |
| In-network deductible | $3,600 |
$800 individual (embedded) $1,600 family |
| Out-of-pocket max | $10,000 family |
$4,000 individual (embedded) $8,000 family |
| Preventive services | 100% Covered | 100% Covered |
| Primary care visit | 20% After Deductible | $20 |
| Specialist visit | 20% After Deductible | $40 |
| Urgent care | 20% After Deductible | $40 |
| Emergency room | 20% After Deductible | $300 + 20% After Deductible |
| Your Monthly Premium | $478 | $863 |
HDHP + HSA:
The High Deductible Health Plan can be paired with a Health Savings Account (HSA), giving you a tax-advantaged way to save and pay for eligible health care expenses.Choice Plus + FSA:
The Choice Plus plan can be paired with a Flexible Spending Account (FSA), allowing you to contribute pre-tax dollars and use those funds for eligible medical expenses.
Choosing between the two plans is a very important and personal decision. As you make your selection, there are many things to consider. See some examples below:
Assess your typical annual health care costs
- Do you anticipate your costs to increase, decrease, or stay the same for the coming year?
- Did you meet your deductible last year?
- How would you have fared if you were on the other plan the previous year—would you have been in a better or worse position?
Consider the tax savings options for each plan
- Both medical plans offer tax-saving opportunities, but the account available depends on the plan you choose.
- Choice Plus plans can be paired with a Flexible Spending Account (FSA). An FSA allows you to set aside pre-tax dollars that can be used toward eligible health care expenses throughout the year. Once enrolled, your annual contribution election generally cannot be changed unless you experience a qualifying life event. If you do not use all of your FSA funds during the plan year, you may carry over up to $680 into the following year. Any amount above the carryover limit will be forfeited.
- The High Deductible Health Plan (HDHP) can be paired with a Health Savings Account (HSA). An HSA allows you to contribute tax-free dollars that can be used toward eligible health care expenses. Unlike an FSA, unused HSA funds roll over from year to year, allowing you to save for future health care needs. HSA funds may also earn interest or be invested, depending on your account balance and investment elections.
- Please see the Tax Savings Accounts section for additional information about these accounts and their features.
Weigh the reward against the risk
- Both plans will provide you and your family with comprehensive medical coverage. Deciding which plan to select may come down to choosing between the reward of spending less in premiums and potential risk of paying more in deductibles and out-of-pocket maximums if you experience a health issue.
To assist with estimating potential out-of-pocket expenses for both plans, an Employee Medical Plan Cost Calculator is available in the Key Resources section of this page. Do the math and determine which plan is the best fit for you and your family’s personal and financial situation.
After your initial medical insurance election with UHC, you should receive a physical ID card via postal mail within 5 – 7 business days of your insurance coverage becoming active. For all subsequent updates to your coverage, new ID cards will only be delivered electronically. You can still request a physical ID card at any time via the myUHC portal or by contacting United Healthcare at 1-844-638-8700.
As health care costs continue to rise, we should look for ways to control costs where we can. With a self-funded plan, both Forvis Mazars and the participants should be wise health care consumers. Please keep in mind the tips below as you weigh your health care options.
Use In-Network Providers
Using in-network providers generates higher discounts, reducing overall plan costs and out-of-pocket expenses.
Seek the Appropriate Level of Care
Seeking the appropriate level of care helps reduce overall plan costs and maintain the continuity of care. An emergency room visit can cost more than seven times what physician’s office or urgent care visits typically cost.
- Take advantage of the 100 percent coverage for preventive care, which may result in early detection and increase prevention awareness.
- Be informed about the cost of tests and treatment plans.
Effective January 1, 2023, eligible employees and partners retiring from the firm can continue to remain on the Forvis Mazars Medical, Dental and Vision plans until they meet the eligibility requirements for Medicare. When the retiree becomes Medicare eligible, their spouse can remain on the plan(s) until they become Medicare eligible. Dependent children can remain on the plan until they reach age 26 or otherwise maintain eligibility.
To be considered a retiree, you must be at least age 52, with the sum of the retiree’s age and years of service (including with a legacy firm) equaling 65 or more and be enrolled in the applicable plan(s) at the time of retirement.
Forvis Mazars does not contribute any funds towards the cost of the retiree coverage. The premiums for retiree coverage are fully paid for by the retiree (or dependents, if applicable). The Medical premiums are 145 percent of the monthly premium for 2027, and the Dental and Vision premiums are 100 percent of the full monthly premium.
HDHP and HDHP CA plans offer discounts for in-network providers, but you will be required to meet your deductible prior to insurance paying. As the name suggests, this plan has a higher deductible, but you will pay less in premiums. This plan may be paired with a Health Savings Account (HSA) for tax savings of approved expenses. Please review the HSA section for more information.
|
Employee Portion |
Firm's Portion |
Monthly Premium |
|
|---|---|---|---|
| Employee Only | $153 | $555 | $ 708 |
| Employee & Spouse | $335 | $1,212 | $1,547 |
| Employee & Child(ren) | $287 | $1,040 | $1,327 |
| Employee & Family | $478 | $1,732 | $2,210 |
| In Network | Out Of Network | |
|---|---|---|
| General Services | ||
| Annual Deductible/Individual | $1,800 | $4,000 |
| Annual Deductible/Family | $3,600 | $8,000 |
| Annual Out-of-Pocket Limit/Individual | $5,000 | $8,000 |
| Annual Out-of-Pocket Limit/Family | $10,000 | $16,000 |
| Office Services | ||
| Office Visit/Exam | 20% After Deductible | 40% After Deductible |
| Specialist Visit | 20% After Deductible | 40% After Deductible |
| Urgent Care | 20% After Deductible | 20% After Deductible |
| Preventive Services | 100% Covered | 40% coinsurance |
| Hospital Services | ||
| Inpatient Hospital | 20% After Deductible | 40% After Deductible |
| Outpatient Surgery | 20% After Deductible | 40% After Deductible |
| Emergency Room Care | 20% After Deductible | 20% After Deductible |
| Emergency Medical Transportation | 20% After Deductible | 20% After Deductible |
| In Network | Out Of Network | |
|---|---|---|
| Retail (30 day supply) | ||
| Generic | $10 After Deductible | No Coverage |
| Brand | $30 After Deductible | No Coverage |
| Non-Formulary | $50 After Deductible | No Coverage |
| Specialty | $200 After Deductible | No Coverage |
| Retail Maintenance (90 day supply) | ||
| Generic | $30 After Deductible | No Coverage |
| Brand | $90 After Deductible | No Coverage |
| Non-Formulary | $150 After Deductible | No Coverage |
| Specialty | Available 30 days retail only | No Coverage |
| Mail Order (90 day supply) | ||
| Generic | $30 After Deductible | No Coverage |
| Brand | $90 After Deductible | No Coverage |
| Non-Formulary | $150 After Deductible | No Coverage |
| Specialty | Available only 30 days retail | No Coverage |
The Choice Plus Plan offer discounts for in-network providers and have set copay amounts for prescription and doctor visits. As a participant utilizing the Choice Plus plan, you will experience lower deductibles but higher premiums. This plan may be paired with a Flexible Spending Account (FSA) for tax savings of approved expenses. Please review the FSA section for more information.
|
Employee Portion |
Firm's Portion |
Monthly Premium |
|
|---|---|---|---|
| Employee Only | $295 | $656 | $951 |
| Employee & Spouse | $646 | $1,433 | $2,079 |
| Employee & Child(ren) | $572 | $1,212 | $1,784 |
| Employee & Family | $863 | $2,109 | $2,972 |
| In Network | Out Of Network | |
|---|---|---|
| General Services | ||
| Annual Deductible/Individual | $800 (embedded) | $1,600 (embedded) |
| Annual Deductible/Family | $1,600 | $3,200 |
| Annual Out-of-Pocket Limit/Individual | $4,000 (embedded) | $7,000 (embedded) |
| Annual Out-of-Pocket Limit/Family | $8,000 | $14,000 |
| Office Services | ||
| Office Visit/Exam | $20 | 40% coinsurance |
| Specialist Visit | $40 | 40% coinsurance |
| Urgent Care | $40 | $40 |
| Preventive Services | 100% Covered | 40% coinsurance |
| Hospital Services | ||
| Inpatient Hospital | 20% After Deductible | 40% coinsurance |
| Outpatient Surgery | 20% After Deductible | 40% coinsurance |
| Emergency Room | $300 + 20% After Deductible | $300 + 20% After Deductible |
| In Network | Out Of Network | |
|---|---|---|
| Retail (30 day supply) | ||
| Generic | $10 | No Coverage |
| Brand | $30 | No Coverage |
| Non-Formulary | $50 | No Coverage |
| Specialty | $200 | No Coverage |
| Retail Maintenance (90 day supply) | ||
| Generic | $30 | No Coverage |
| Brand | $90 | No Coverage |
| Non-Formulary | $150 | No Coverage |
| Specialty | Available 30 days retail only | No Coverage |
| Mail Order (90 day supply) | ||
| Generic | $30 | No Coverage |
| Brand | $90 | No Coverage |
| Non-Formulary | $150 | No Coverage |
| Specialty | Available only 30 days retail | No Coverage |
| In Network | Out Of Network | |
|---|---|---|
| Retail (30 day supply) | ||
| Generic | $10 After Deductible | No Coverage |
| Brand | $30 After Deductible | No Coverage |
| Non-Formulary | $50 After Deductible | No Coverage |
| Specialty | $200 After Deductible | No Coverage |
| Retail Maintenance (90 day supply) | ||
| Generic | $30 After Deductible | No Coverage |
| Brand | $90 After Deductible | No Coverage |
| Non-Formulary | $150 After Deductible | No Coverage |
| Specialty | Available 30 days retail only | No Coverage |
| Mail Order (90 day supply) | ||
| Generic | $30 After Deductible | No Coverage |
| Brand | $90 After Deductible | No Coverage |
| Non-Formulary | $150 After Deductible | No Coverage |
| Specialty | Available only 30 days retail | No Coverage |
| In Network | Out Of Network | |
|---|---|---|
| Retail (30 day supply) | ||
| Generic | $10 | No Coverage |
| Brand | $30 | No Coverage |
| Non-Formulary | $50 | No Coverage |
| Specialty | $200 | No Coverage |
| Retail Maintenance (90 day supply) | ||
| Generic | $30 | No Coverage |
| Brand | $90 | No Coverage |
| Non-Formulary | $150 | No Coverage |
| Specialty | Available 30 days retail only | No Coverage |
| Mail Order (90 day supply) | ||
| Generic | $30 | No Coverage |
| Brand | $90 | No Coverage |
| Non-Formulary | $150 | No Coverage |
| Specialty | Available only 30 days retail | No Coverage |
Have questions about your pharmacy benefits? Answers are just a click away!
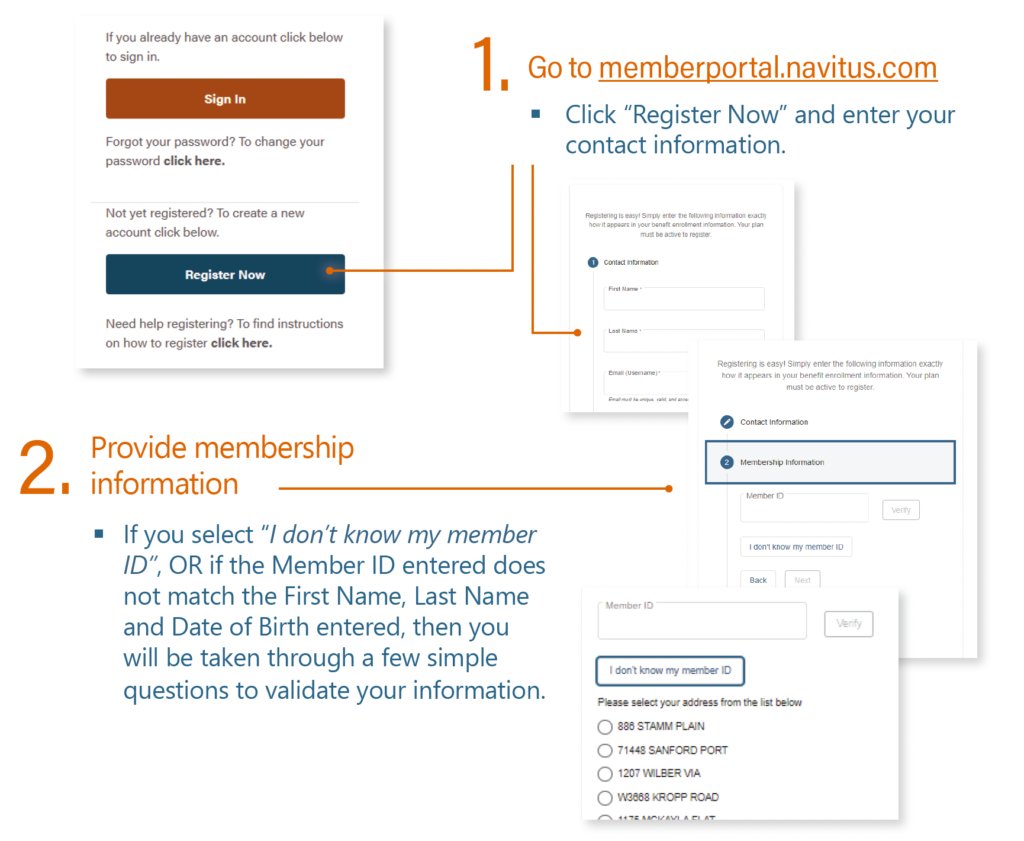
Tools to help you make the most of your pharmacy benefits are at your fingertips, 24 hours a day, 7 days a week. Log in to Navitus’ secure member portal at www.navitus.com or visit your plan’s website for access to:

How to Register on the Member Portal

2nd.MD
You can receive a FREE second opinion from a top specialist via video or phone call and 2nd.MD will help manage the process for you.
Virtual Care Visits
UnitedHealthcare makes it easy to access quality care from the comfort of your home—day or night. Through 24/7 Virtual Visits, you can connect with board-certified doctors and licensed therapists using your smartphone, tablet, or computer.
Medicare
If 65 is just around the corner, it’s time to start thinking about Medicare!

Key Resources
General Information
Pharmacy Benefits and Coverage
Preventive Services
To use this document:
- Request the CPT codes from the ordering physician they will use when filing the claim.
- Search the document for the code.
- If the code is found, the criteria (e.g., age or gender related) will be listed considered preventive.
- If the code is not found, this indicated it will be considered diagnostic.
Annual Notices
- Summary Annual Report (SAR)
- CHIP - Model Notice
- Employee Rights & Responsibilities under FMLA
- Forvis Mazars Illinois Disclosure
- General COBRA Notice
- HIPAA Comprehensive Notice of Privacy Policy & Procedures
- Medical Part D Creditable Coverage Notice
- New Health Insurance Marketplace Coverage Options & Your Health Coverage
- Notice for Employer-Sponsored Wellness Programs
- Notice of Special Enrollment Rights
- Women's Health & Cancer Rights Notice
- Notice of Right to Designate Primary Care Provider and of No Obligation for Pre-Authorization for OBGYN Care
- 1557 Nondiscrimination and Languages / Accessibility Notices